Anthropic has filed to go public. The Claude maker’s Form S-1 went up on the SEC’s EDGAR system on Monday, October 26, at 9:00 AM ET, and it says the company has applied to list its Class A common stock on the Nasdaq Global Select Market under the symbol “ANT.” The Anthropic IPO filing also opens the company’s books for the first time. Revenue for the first half of 2026 was $16.29 billion, up from $1.16 billion in the same half of 2025.
What the filing doesn’t have is a price. The cover page leaves the price range and the share count blank, and Anthropic’s own announcement says both “have not yet been determined.” So nobody can buy ANT shares yet, and any valuation you’ve seen on X didn’t come from this document.
- What was filed: a preliminary Form S-1 for an initial public offering of Anthropic, PBC’s Class A common stock, made public October 26, 2026. Goldman Sachs and Morgan Stanley are the lead underwriters, and existing stockholders will also sell shares.
- Ticker: Anthropic has applied to list on the Nasdaq Global Select Market as “ANT.”
- When you can buy: not yet. The prospectus says the shares can’t be sold until the registration statement is effective. There’s no price range, share count or IPO date in the filing.
- The catch: Class A shares get one vote each, but all Class A holders together are capped at 49.9% of the votes. An entity owned by the seven co-founders holds 50.1%, and a trust elects a majority of the board.
What the Anthropic IPO filing shows about revenue
The “Summary Consolidated Financial and Other Data” table shows revenue of $41 million in 2023, $386 million in 2024 and $4.59 billion in 2025. In the six months ended June 30, 2026, it was $16.29 billion, which Management’s Discussion and Analysis (MD&A) calls a 1,300% increase. The quarterly table shows how steep the curve got: $4.73 billion in the first quarter of 2026, then $11.56 billion in the second.
Most of that money is metered usage. MD&A says consumption-based revenue, which Anthropic calls “pay-for-intelligence,” was $13.1 billion, or 80% of total revenue, in the first half of 2026. Subscriptions brought in $3.2 billion, the other 20%. So the “80% usage-based” figure going around X checks out, for that period. In 2025 the usage share was 83%.
The Prospectus Summary adds customer numbers, which are Anthropic’s own operating metrics. It claims more than 11,900 customers that paid at least $100,000 over the trailing 12 months as of September 30, 2026, and more than 1,900 that paid $1 million or more. It also says that $100,000-plus group includes every company in the Fortune 10.
The $80.7 billion loss is mostly a paper charge
The headline loss is huge: $80.75 billion for the first half of 2026, after $41.97 billion for all of 2025. The operating line tells a different story. The operating loss for the half was $693 million, and the second quarter shows $974 million of operating income, the first positive quarter in the filing’s quarterly table.
The gap is a $72.4 billion charge for changes in the fair value of convertible notes and similar instruments. The filing says it was “primarily driven by an increase in the fair value of our outstanding convertible promissory notes resulting from an increase in our enterprise valuation.” Put simply, as Anthropic became more valuable, the notes it owes investors got more expensive on paper. It’s a non-cash charge. As of June 30, the company says it had raised $141.1 billion in total and held $112.4 billion in cash and cash equivalents, plus $19.3 billion in short-term investments.
Where the money goes: compute deals worth hundreds of billions
The biggest numbers in the S-1 are compute commitments, listed in MD&A’s liquidity section. Anthropic says it has committed to spend at least $110.0 billion with Amazon between May 2026 and April 2036, about $114.5 billion with Google between April 2026 and July 2033, and at least $44.9 billion with Microsoft between November 2026 and May 2033, all “regardless of actual usage.” It separately estimates $125.0 billion to $150.0 billion for extra TPU capacity from 2028 to 2031, which isn’t in its commitments table.
Compute and infrastructure cost $8.9 billion in the first half of 2026. Anthropic’s pitch is that revenue is outrunning it: the Prospectus Summary claims revenue grew 1,368% year over year in the second quarter while compute and infrastructure expenses grew 300%.
Who controls Anthropic after the IPO
Anthropic is a Delaware public benefit corporation, so its board has to weigh shareholder returns against its stated purpose, “the responsible development and maintenance of advanced AI for the long-term benefit of humanity.” The filing describes a Long-Term Benefit Trust of five financially disinterested trustees. Through one share of Class T stock, the trust elects and removes the Class T directors, who will be a majority of the board.
A single share of Class F stock goes to a Founder LLC whose members are the seven co-founders, including CEO Dario Amodei and President Daniela Amodei. That share carries 50.1% of the total vote and no economic rights. Class N stock, held mainly by strategic partners, has no vote; Risk Factors says Amazon and Google will each hold more than 5% of the company after their notes convert. Anthropic will be a “controlled company” under Nasdaq rules. If you buy ANT, you’re buying a share of the economics, not a say in how the company is run.
The risks Anthropic lists
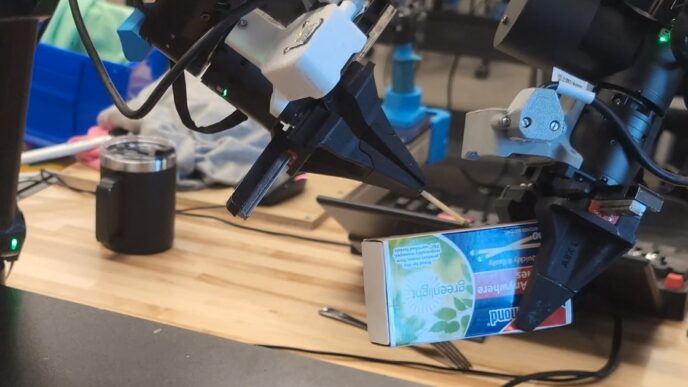
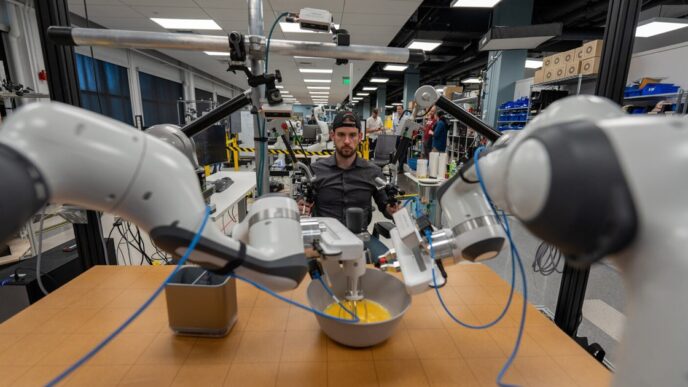
A few disclosures stand out. Anthropic says its top five customers made up about 25% of revenue in the nine months to September 30, 2026, though none topped 10%. It also estimates that about 5% to 7% of revenue in that period came from customers it later found were violating its usage policy or commercial terms, and it expects that share to fall. There’s a robotics thread too: the filing says Anthropic is “extending Claude into robotics,” with a research-preview Model Hardware Standard that lets agents run lab equipment and off-the-shelf robotic arms.
Insiders can’t sell right away. Co-founders and holders of more than 0.5% of fully diluted shares are locked up until shortly after the third-quarter 2027 results or for 365 days, whichever comes first. Other holders get 180 days or the first-quarter 2027 results. The lead underwriters can release shares early.
What the filing leaves blank, and what to watch
Several things you might expect aren’t in the S-1. There’s no price range or share count, and no valuation. Third-quarter 2026 revenue and Anthropic’s run-rate revenue figure are left blank, to be filled in later. The $1 billion in the filing-fee exhibit is a placeholder “estimated solely for the purpose of computing the amount of the registration fee,” not the deal size. The $1.5 trillion to $2 trillion valuation and mid-November listing dates circulating on X don’t appear anywhere in the filing.
The next step to watch for is an amended S-1 on EDGAR with a price range and share count. A roadshow, the SEC declaring the registration effective, and pricing would follow. Only after pricing would ANT start trading, and only then could most people buy it through a regular brokerage account.
Frequently asked questions
When can I buy Anthropic stock?
Not yet. Anthropic filed a preliminary S-1 on October 26, 2026, and the prospectus says the shares may not be sold until the registration statement becomes effective. The filing gives no IPO date and no price range. Shares would start trading only after the offering is priced.
What is Anthropic’s stock ticker?
Anthropic has applied to list its Class A common stock on the Nasdaq Global Select Market under the symbol ANT.
How much revenue does Anthropic make?
According to the S-1, Anthropic had $16.29 billion in revenue in the six months ended June 30, 2026, and $4.59 billion in all of 2025. About 80% of first-half 2026 revenue was usage-based.
What is the Anthropic IPO price or valuation?
The filing doesn’t say. The price range and share count are blank, and Anthropic says they haven’t been determined. The $1 billion in the filing-fee exhibit is only used to calculate the SEC registration fee.
Is Anthropic profitable?
Not on a net basis. The S-1 shows $974 million of operating income in the second quarter of 2026, but a net loss of $80.75 billion for the first half, mostly from a $72.4 billion non-cash charge on convertible notes.
Sources
- Anthropic, PBC, Form S-1 registration statement (filed October 26, 2026; accession 0001628280-26-067168). Sections used: cover page, Prospectus Summary, Summary Consolidated Financial and Other Data, Risk Factors, Management’s Discussion and Analysis of Financial Condition and Results of Operations (revenue mix, quarterly results, liquidity and contractual obligations), Principal and Selling Stockholders, Underwriting: sec.gov
- SEC EDGAR filing index for the S-1, including the filing-fee exhibit: sec.gov
- Anthropic, “Anthropic files S-1 with the SEC for proposed initial public offering” (October 26, 2026): anthropic.com
- Anthropic on X, S-1 announcement (October 26, 2026, 9:05 AM ET): x.com/AnthropicAI
All sources checked on the morning of October 27, 2026 (ET). The S-1 is a preliminary prospectus and may be amended.
Last updated: October 27, 2026. To report an error, see our corrections page. Articles are drafted with AI assistance and reviewed and edited by an editor; see our editorial policy.